Cash Flow & Working Capital Advisory
For growing UAE businesses, see where cash is tied up, anticipate pressure and act before growth puts liquidity under strain.
An illustrative 13-week cash outlook highlights a pressure window, a minimum cash buffer and upcoming customer receipts, payroll and supplier payments.
Profit can look healthy while cash is already tightening
Revenue, profit and cash do not move at the same time. A growing business can report a profit while customer receipts arrive after payroll, suppliers, tax payments, inventory purchases and other commitments fall due. New contracts can also consume cash during delivery before the related receipts are collected.
If management relies on memory or a spreadsheet updated only when pressure rises, cash flow visibility is already too reactive.
This is market context rather than a measure of any individual business. It reinforces why realistic receipt assumptions, customer payment behaviour and collection discipline matter to forward cash visibility and working capital.
A controlled cash view should answer:
When is customer cash expected to arrive?
What cash must leave the business, and when?
Where is cash tied up in the operating cycle?
What changes if receipt or payment timing moves?
What can management change now?
Cash pressure starts before it reaches the bank balance
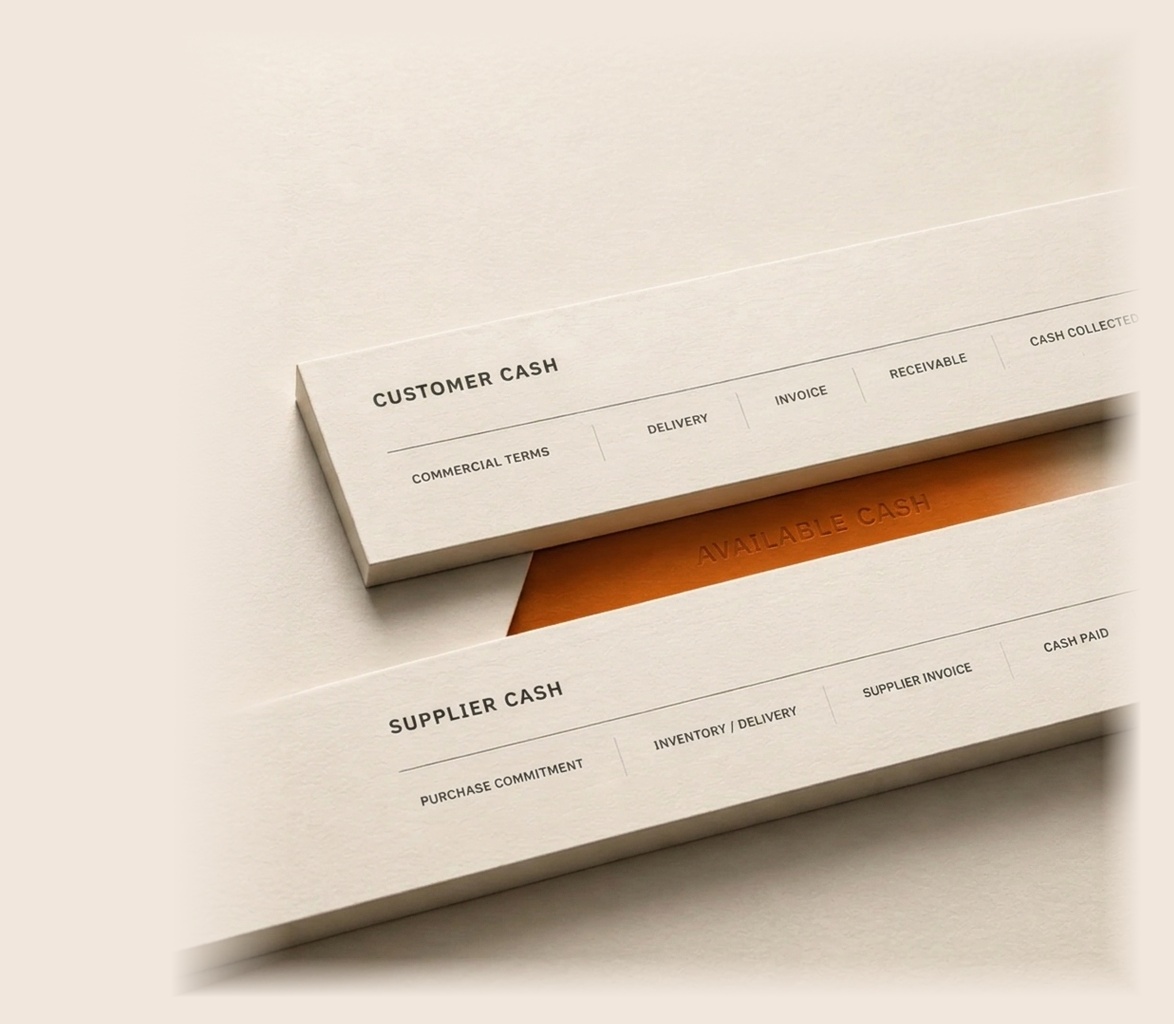
Cash timing is shaped before money reaches or leaves the bank. Commercial terms, billing, inventory, purchasing and supplier decisions determine when revenue converts to cash and when commitments become payments.
Credit terms, billing accuracy and dispute resolution influence how quickly revenue converts to cash.
Inventory levels, purchase timing and mobilisation can absorb cash before the related receipts arrive.
Commitments, payment terms and payment scheduling determine when cash leaves the business.
Finance sees the result. Operations create the timing.
See where cash is tied up
in the operating cycle
Average time customers take to pay.
Average time inventory remains
on hand before sale.
Average time the business takes
to pay suppliers.
Cash Conversion Cycle = DIO + DSO − DPO
Together, these measures show how long operating cash remains tied up and where management may be able to release it.
JUDGEMENT MATTERS
Optimise the cycle, not a single metric. Customer terms, supplier relationships, inventory availability and continuity of supply all matter.
From cash visibility to repeatable control
Build the cash position
Cash balances, receipts and commitments
Identify cash pressure
Receivables, supplier timing and working capital
Set cash priorities
Collections, cash buffer and spending timing
Make control repeatable
Scenarios, ownership and forecast review
13-week cash forecast | Assumptions register | Receivables & payables analysis | Prioritised cash action plan
If records are incomplete or unreliable, we flag the limitation before finalising recommendations.
Start with the cash problem
13-Week Cash Visibility
Receipts, commitments and near-term pressure are not reliably visible.
Working Capital Diagnostic
Receivables, inventory or supplier timing is absorbing cash.
Ongoing Cash Control
Forecasting exists, but ownership or review discipline is inconsistent.
What experienced cash management catches early
Collections begin before an invoice is overdue
Credit terms, billing accuracy and early dispute resolution can influence collection timing long before an invoice reaches collections.
Growth can consume cash before it generates it
Contracts, inventory, hiring and mobilisation can require cash before customer receipts arrive.
Longer payment terms are not automatically better
Liquidity gains must be balanced against supplier relationships, commercial terms and continuity of supply.
Cash timing depends on howthe business actually operates
CUSTOMER RECEIPTS
Contract terms, billing accuracy and customer payment behaviour determine when revenue becomes available cash.
FIXED COMMITMENTS
Payroll, tax, suppliers and other scheduled obligations create cash requirements that do not necessarily move with reported profit.
GROWTH CASH
Recruitment, inventory and project mobilisation can absorb cash before the related customer receipts arrive.
Cash Flow & Working Capital Advisory does not include lending, financing brokerage, legal debt recovery or insolvency services.
DIRECT SENIOR INVOLVEMENT
Senior finance expertise stays close to key decisions.
CONNECTED FINANCE VIEW
Accounting, reporting, forecasts and operations considered together.
DECISION-READY OUTPUTS
Focused outputs for liquidity, working capital and management decisions.
BUILT FOR GROWING BUSINESSES
Designed around the finance needs of UAE startups, SMEs and growing businesses.
Cash Flow & Working Capital FAQs
It is forward-looking financial support that helps management understand expected cash receipts and payments, identify potential liquidity pressure and examine how receivables, inventory and supplier-payment processes affect available cash.
Cash flow concerns the timing and movement of cash, while operating working capital concerns cash tied up in receivables and inventory, offset by supplier payables.
A 13-week cash flow forecast is a weekly view of expected receipts, payments and closing cash over approximately one quarter. It is commonly used when management needs detailed short-term visibility. The appropriate forecasting horizon depends on the business and the decisions being supported.
The update rhythm depends entirely on the business environment and management needs. A business navigating tight liquidity might require weekly rolling updates. A stable business seeking general visibility might review monthly.
A cash flow statement explains historical cash movement during a completed period. A cash flow forecast estimates future receipts and payments using current information and documented assumptions. Historical cash reporting belongs within Management Accounts & Reporting. Forward-looking liquidity analysis belongs within this advisory service.
The starting information commonly includes bank balances, receivables and payables, payroll, recurring costs, supplier commitments, tax payments, inventory information, expected customer receipts and details of material planned decisions. Requirements depend on the business and agreed scope.
Scope depends on the number of entities and bank accounts, the quality of available information, whether inventory or project activity is material, the forecasting detail required and whether the need is a one-time diagnostic or an ongoing review process. The scope and fee are agreed after the initial situation is understood.
Cash Flow and Working Capital Advisory addresses a defined specialist need involving liquidity visibility and working-capital actions. Fractional CFO Services provide broader and continuing senior finance leadership, management challenge and integrated financial oversight.
See the cash position clearly. Know what to do next.
Tell us where cash visibility is limited or pressure is building. We will help identify what needs attention first.