Management Accounts & Reporting That Show What Drives Your Business
Monthly or quarterly management reporting for UAE startups, SMEs and growing businesses, built to show what changed, where performance moved and what management needs to see clearly.
Your Accounts Are Closed. Can You Explain What Changed?
Management accounts turn closed books into a clear view of performance, showing what moved, where it happened and what needs attention.
What changed in revenue, margin, costs, profit and cash?
How does performance compare with budget or the prior period?
Which branch, product, customer or project drove the result?
What You Receive Each Reporting Period
A reporting pack built around how the business operates, what management needs to see and the comparisons that matter.
Core Financials
Profit and loss, balance sheet and historical cash movement for the agreed reporting period.
Cash and Working Capital
Cash movement, receivables, payables ageing, inventory and other relevant balance movements.
Performance Summary
A concise view of revenue, margins, costs and material movements across the reporting period.
Management Commentary
Clear explanation of significant variances, exceptions and matters requiring management attention, with provisional figures identified where relevant.
See What Moved Against Plan and Why
Current results compared with relevant prior periods and with an approved budget or target where one already exists.
Budget vs Actual
Is budget versus actual shown only where an approved budget or target exists?
Variance Analysis
Material variances should distinguish timing differences, one-off items and supported changes in trading performance.
Management Commentary
Does the commentary explain material movements without forcing unsupported conclusions?
See More Than the Company Total
Business-wide totals can hide where performance is improving, where margins are under pressure and where value is being created or lost. Where the underlying records support reliable allocation, management reporting can show performance by entity, location, product, customer, project or department.
Entity or Subsidiary
Compare revenue, costs, margins and financial performance across individual legal entities within a wider group structure.
Branch or Location
Compare revenue, operating costs, margins and performance across individual branches, locations or operating sites.
Product or Service Line
Understand revenue, direct costs and margin contribution across individual products, services or business lines.
Customer or Sales Channel
Compare revenue, gross margin, receivables and profitability across customers, customer groups or sales channels.
Project or Contract
Track revenue, costs, billing and profitability by individual project, engagement or contract.
Department or Cost Centre
Monitor expenditure, budget performance, resource allocation and cost ownership across departments or functional areas.
Segment reporting is used only where the underlying records and source data can support a reliable allocation. Where they cannot, we identify the limitation before presenting a result that could mislead management. Internal reporting does not replace formal consolidated financial statements prepared under applicable IFRS requirements.
Track the Measures That Actually Matter
Focused financial and operational KPIs, clearly defined and reliably sourced from your underlying records.
Relevant
Tied directly to the operating decisions management needs to make.
Defined
Calculated the exact same way across every reporting period.
Reliable
Sourced consistently from the underlying accounting records.
Reporting That Arrives in Time to Be Useful
The appropriate reporting frequency depends on how often management needs reliable information to review performance and make operating decisions.
Monthly
Regular visibility over performance, cash, working capital, margins and material movements. Usually appropriate where management needs timely information throughout the year.
Quarterly
A lighter reporting cadence that may suit simpler or more stable businesses where management decisions do not require the same level of monthly financial visibility.
Does Your Current Pack Answer the Questions Management Actually Has?
Use these questions to review whether the information reaching management is timely, connected and specific enough to support decisions.
Timetable
Is the pack issued to an agreed timetable after the accounting period is closed?
Core Visibility
Are revenue, margins, costs, profit and actual cash movement clearly visible?
Comparisons
Are current results compared on a consistent basis with relevant prior periods?
Decision Level
Can management see performance at the level where decisions are made?
Open Items
Are unusual, missing or provisional items kept visible?
Management Accounts & Reporting Questions
Management accounts are recurring internal financial reports prepared to help owners and management understand how the business is performing. They typically bring together financial results, comparisons, KPIs and commentary so management can see what changed, where performance moved and what requires attention. They are also commonly referred to as management reporting or MIS reporting.
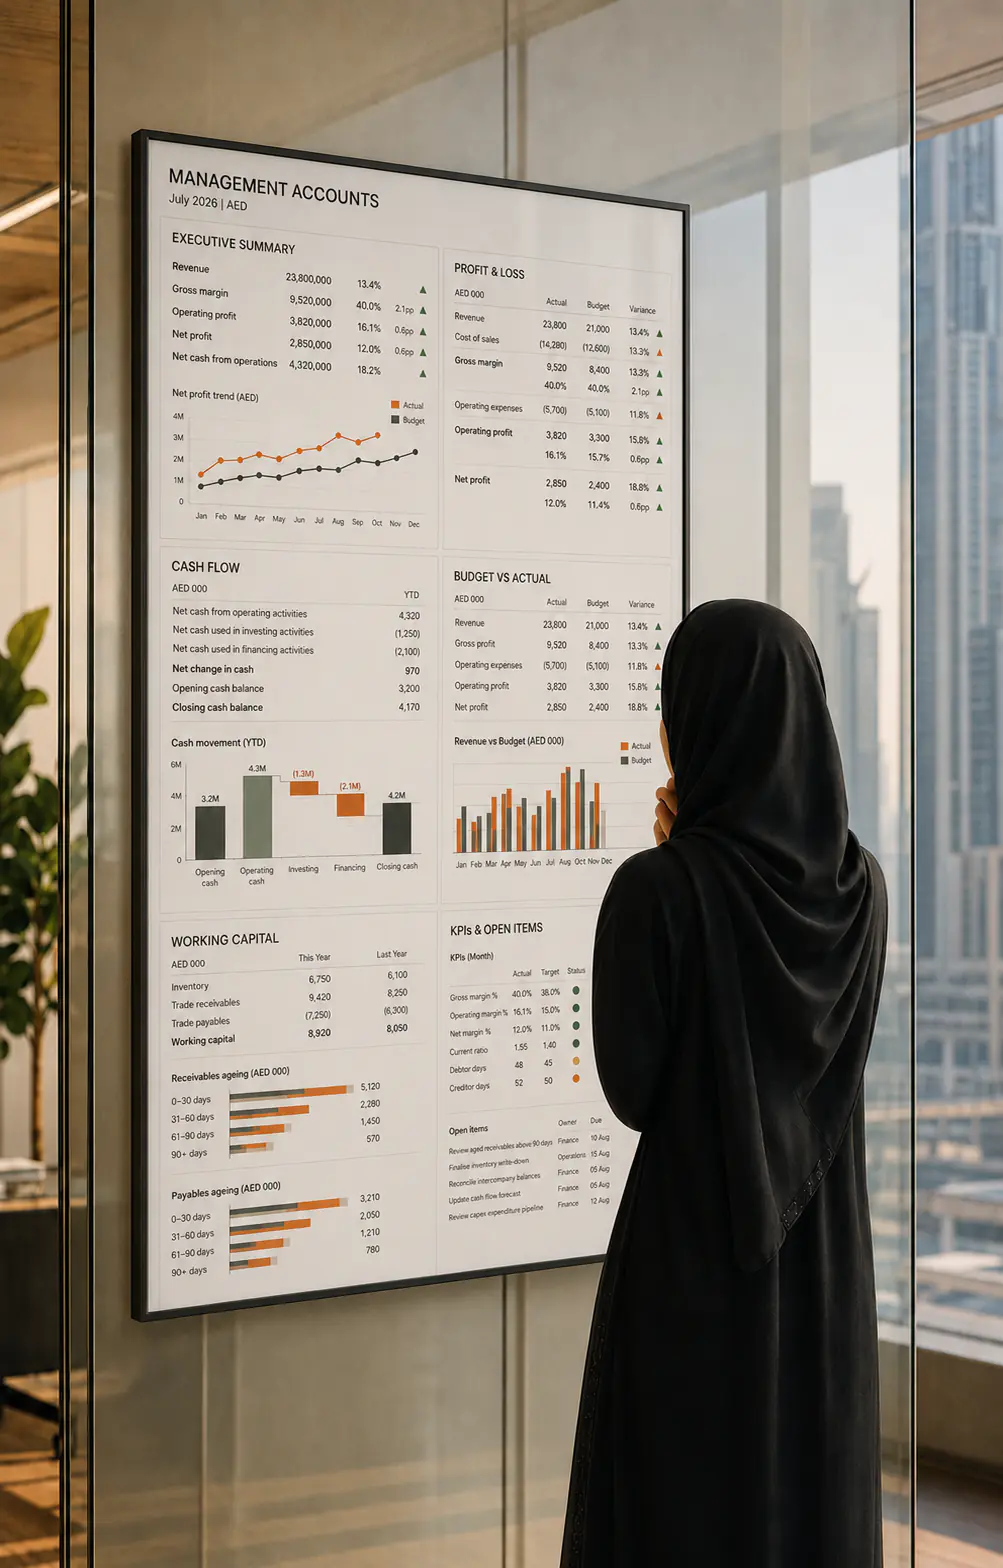
The exact reporting pack depends on the business, but it may include profit and loss, balance sheet, historical cash movement, budget or prior-period comparisons, working capital information, agreed KPIs, reporting by relevant business dimension and concise management commentary. The objective is not to produce more reports, but to present the information management actually needs.
Bookkeeping focuses on maintaining accurate accounting records, posting transactions, reconciling balances and supporting the close process. Management accounts build on those closed records by organising and interpreting the information through comparisons, KPIs, reporting dimensions and commentary. Bookkeeping establishes the financial record. Management accounts help management understand performance.
Management accounts are internal reports prepared at an agreed frequency for management use and can be tailored around how the business operates. IFRS financial statements are formal financial statements prepared in accordance with applicable IFRS requirements for external reporting or stakeholder needs where required or requested. Management accounts do not replace formal IFRS financial statements.
Monthly reporting is generally more useful where revenue, margins, cash, collections, costs or operational activity can change materially from one month to the next. Quarterly reporting may suit a simpler or more stable business that needs a higher-level view. The appropriate frequency depends on management needs, the close process and the availability of reliable data.
Pricing depends on the specific reporting scope, frequency, number of entities, reporting dimensions, condition of the underlying accounting records, KPI requirements and level of analysis or commentary required. The engagement may be recurring monthly or quarterly reporting, or form part of a broader outsourced finance arrangement. We agree the scope and pricing around the reporting needs of the business rather than applying one standard fee model.
Budget versus actual reporting can be included where an approved budget or target already exists. Preparing a new budget, building financial forecasts, developing financial models or providing ongoing strategic finance leadership are separate advisory activities and are agreed separately where required.
Yes. Management reporting can sit on top of accounting records maintained by your internal finance team, existing accountant or outsourced bookkeeping provider. We first confirm that the underlying records are sufficiently complete and reconciled, then agree the reporting structure, data inputs, timetable and responsibilities with the relevant team.
We need sufficiently current and reconciled accounting records, together with the information required for the agreed reporting pack. This may include an approved budget or comparison period, KPI definitions, reporting dimensions and relevant management inputs. If the underlying records are behind, incomplete or unreconciled, the accounting position should first be brought to a reliable starting point before recurring management reporting begins.
Turn Reporting Into Better Decisions
Tell us what management needs to see each month. We will shape a reporting approach around the financial information and KPIs that matter to your business.